Knowing we have a ton of flying ahead of us, the dread of long airport layovers suddenly hit me.
During a past trip, We tried using Korean Air lounge coupons while flying Korean Air on a ticket booked with Delta miles—and got turned away at the door because of the Delta booking. That was our ultimate wake-up call. We needed a card strategy that could get our family of three into airport lounges hassle-free for our upcoming world tour.
Why Popular Premium Cards Didn’t Work for Us
Naturally, my initial search pointed to the big-name premium travel cards:
Capital One Venture X ($395 Annual Fee, 2026): They recently cut back on free guest access perks for lounge visits.
Chase Sapphire Reserve ($795 Annual Fee, 2026): Offsetting the annual fee requires tracking monthly or quarterly dining and other credits—way too much maintenance for our taste.
Amex Platinum ($895 Annual Fee, 2026): The high annual fee simply doesn’t justify the perks for our specific spending style.
The Ultimate Workaround: Upgrading to the Ritz-Carlton Card
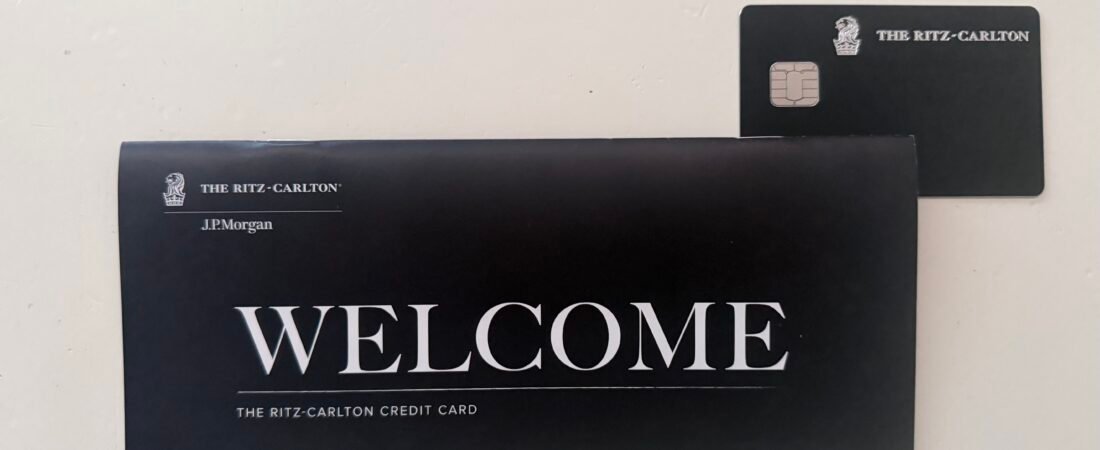
For years, We’ve held the Chase Marriott Bonvoy Boundless Card mostly for its annual 35k free night certificate. Since we don’t use it constantly, we called Chase and requested a product change to the Chase Ritz-Carlton Credit Card.
If you want to try this product change workaround, keep these rules in mind:
No Direct Sign-ups: The Ritz-Carlton card is closed to new applicants, but you can still get it by upgrading an existing Chase Marriott card.
1-Year Rule: You must hold the Chase Bonvoy Boundless card for at least 1 year before requesting a product change.
Credit Limit Requirement: Your Boundless card needs a minimum $10,000 credit limit. If yours is lower, you can easily shift credit lines from your other personal Chase cards at the time of product change.
Why the Ritz-Carlton Card Wins for Family Travel
The $450 annual fee might sound steep at first, but the math works out heavily in our favor:
Unbeatable Lounge Access: The included Priority Pass (PP) covers the primary cardholder plus 2 guests for free. Even better, authorized users get their own free Priority Pass with the same 2-guest privileges. It also grants access to Chase Sapphire Lounges.
$300 Airline Incidental Credit: Even though this is not automatic credit to your account, you can easily request this via secure message or phone call. It covers seat upgrades and checked bag fees. Since we expect to pay checked bag fees on regional airlines during this trip, we’ll max out this $300 credit with zero waste.
85k Free Night Award: Recurred annually, this single perk easily covers the remaining effective cost of the card.
Setting Up Our Child for the Future (And Easy Transit!)
Since we’ll be using public transit in Seattle, I discovered you can simply tap-to-pay with a contactless credit card—no extra transit card or registration required for visitors. This also works in other big cities, such as New York.
To make our travel even smoother, and each person needs a card at the transit (doesn’t have to be their own), I requested an authorized user card in our child’s name. Even though he is currently under 12 years old, Chase allowed you to add the minor children as an authorized user.
This isn’t just about handing them a card for contactless transit; it’s a major head start for their financial future. Credit history starts accumulating from the moment the card is issued, regardless of how much they actually use it. By building a solid credit file now, we’re giving our child a huge leg up for when they reach adulthood.
To be honest, we haven’t even stepped foot near a real Ritz-Carlton hotel yet, but I have a feeling this card is going to be a total lifesaver for our travels!